Mortgage advice you can trust

Let me navigate you through the process of successfully achieving your mortgage goals

LET'S TALK
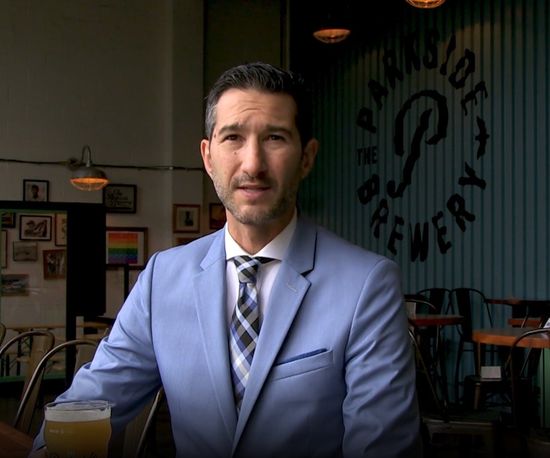
MICHAEL HALLETT 
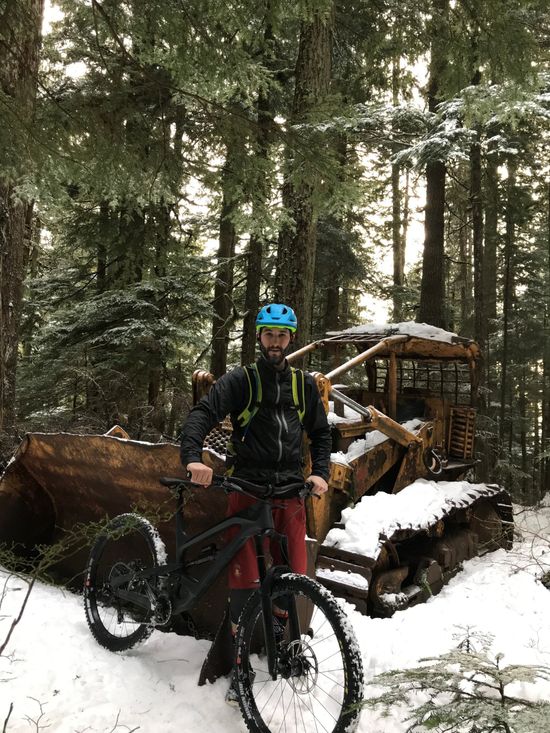
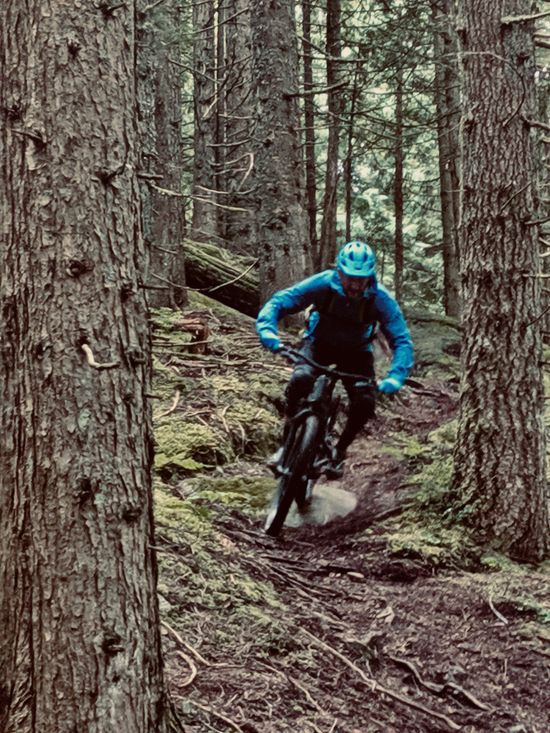
Passionate about Mortgages, Mountain Biking and Craft Beer

Mortgage financing can be frustrating. It doesn't have to be when you follow this 3 step plan.

Get started right away

The best place to start is to connect with me directly. The mortgage process is personal. My commitment is to listen to all your needs, assess your financial situation, and provide you with a clear plan forward.

Get a clear plan

Sorting through all the different mortgage lenders, rates, terms, and features can be overwhelming. Let me cut through the noise, I'll outline the best mortgage products available, with your needs in mind.

I'll handle the details

When it comes time to arranging your mortgage, I have the experience to bring it together. I'll make sure you know exactly where you stand at all times. No surprises. I've got you covered.
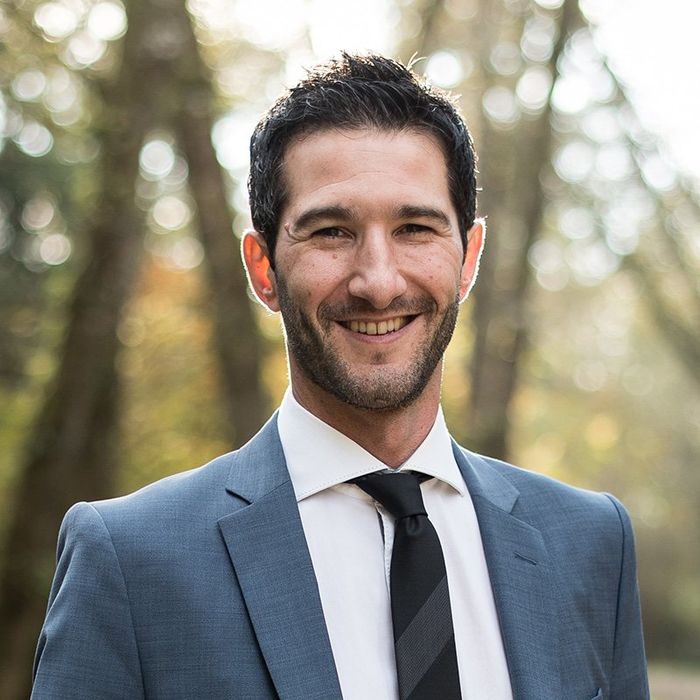
MICHAEL HALLETT

Mortgage Broker

Thank you for coming to check my website. If you only have time to read one paragraph, I can summarize everything below in one sentence. I’m a 13-year veteran mortgage broker, addicted mountain biker for over 26 years, passionate big mountain skier for even longer, rookie dirt biker, outdoor enthusiast for over 45 years and lover of craft beer.


As a BC boy born and bred, I can proudly say I’ve lived my entire life in BC. Growing up on the north end of Vancouver Island in a small logging town (Holberg), it helped cement my love for the outdoors. From there we moved to the Coquitlam area when I was 10 years old where my dad opened a business with my uncle.


After graduating high school, I moved to Victoria for 1 year where I enrolled in an Outdoor Eco-tourism Program. From there my then girlfriend and I, now my wife Kirstin, moved to Whistler to pursue a lifestyle of playing and working outside. It was there that my entrepreneurial spirit had started to take shape. Over the next couple of years, I self-started two small businesses in the tourism industry including a guided mountain bike adventure company.


It was around this time in Whistler that Kirstin and I bought our first home and I started to become interested in the mortgage financing space. Our son Aidan was born in 2007 and a year later we decided to move back to Coquitlam to pursue different careers. After purchasing our second home in 2008, I knew that I wanted to make a career out of being a Mortgage Broker, so I did. I have been assisting clients achieve their goals of real estate ownership since August 2009. Currently I am ranked in the top 5% of brokers at Dominion Lending across Canada. In 2021 I received the DIAMOND award for my mortgage practice.


When we are not working or Aidan’s not in school you can usually find us being active somehow; hiking, mountain biking, skiing, camping, boating, playing hockey, golfing, traveling or on the road headed out on our next adventure. We love being busy and we would not have it any other way!

On a more personal note...

BEERS, BIKES & MORTGAGES

I am passionate about mortgage brokering, mountain biking and craft beer.


My commitment is to navigate you through the entire mortgage process, guiding you every step of the way. I have the ability and experience to help you achieve your mortgage goals.


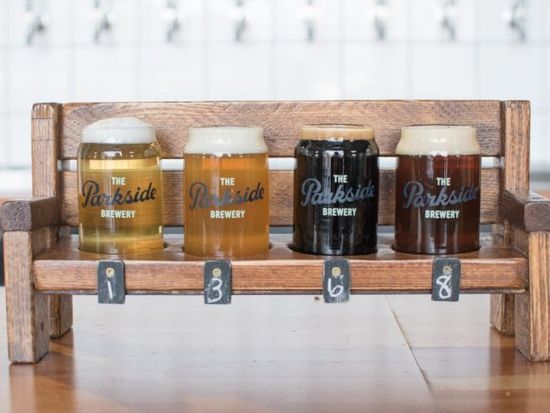
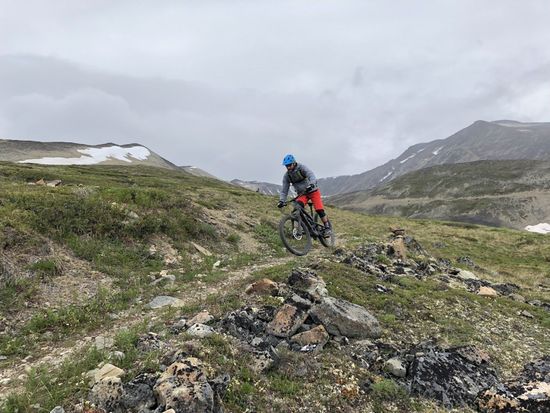
Mountain biking is a true lifestyle and I absolutely love it. I also enjoy good tasting beer and Parkside Brewery is one of my favorite places.


Watch my 'Beers, Bikes & Mortgages' video here.
Obviously there are a lot more services I can offer and a lot more information I can share with you. Consider this my invitation to contact me with your questions, I would love to work with you and help you figure out a plan not only to get you a mortgage, but to help you get rid of it.

BURKE MOUNTAIN DEVELOPMENTS

If you are looking to purchase a home in the new Burke Mountain Development, I know the project very well and would love to help you arrange mortgage financing. I live in Coquitlam and spend most of my free time in Pinecone Burke Mountain Provincial Park. If you are looking for an inside man to help you navigate the area, you’ve found him.

Okay, so maybe a calculator really isn’t a service, but if you click through this link, it will take you to a page with a some really fun options to run some calculations on your own. When you have things somewhat figured out, give me a shout and we can see exactly where you stand.
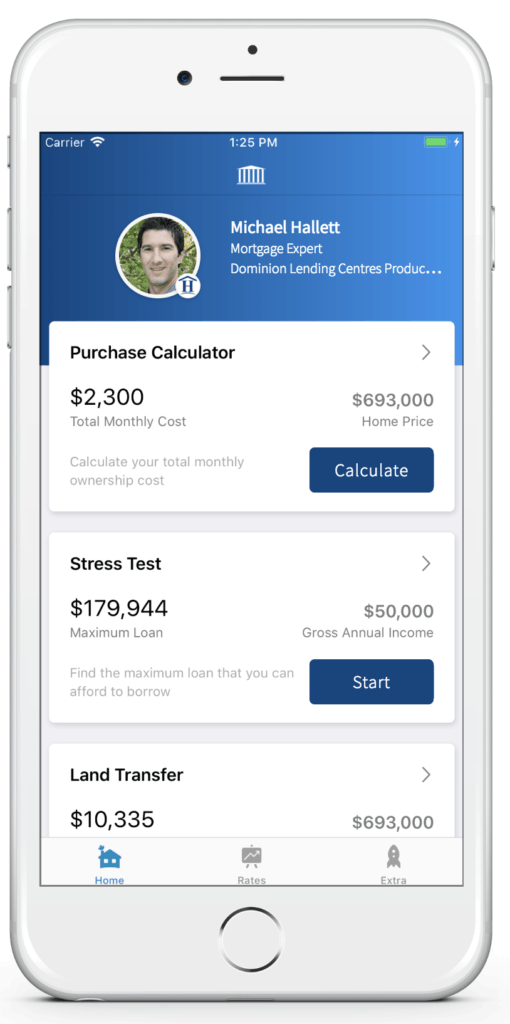
DOWNLOAD MY MORTGAGE TOOLBOX


WHAT CAN YOU DO WITH MY APP:


  • Calculate your total cost of owning a home
  • Estimate the minimum down payment you need
  • Calculate Land transfer taxes and the available rebates
  • Calculate the maximum loan you can borrow
  • Stress test your mortgage
  • Estimate your Closing costs
  • Compare your options side by side
  • Search for the best mortgage rates
  • Email Summary reports (PDF)
  • Use my app in English, French, Spanish, Hindi and Chinese
 

TESTIMONIALS

It was definitely a pleasure working with Michael. From day one he was upfront and honest about my unique credit situation, however he was also the positive reinforcement I needed to keep going and give it a try. Even when the banks wouldn’t give me the time of day, he was certain we would find someone who would give me a chance. He was very patient with my questions (I am sure they seemed to be never-ending at times), and helped to guide me through the many different stages of purchasing a home.

Thanks to Michael and his dedication, he found a lender that would work with my situation and I now own my first home. He also has coached me on how to fix my credit rating, and I am pleased to say that my credit score is already considerably higher than when we began this process. I would highly recommend Michael to anyone looking for a mortgage!

Jillian

As first time home buyers, we had many questions and concerns. Even if not directly related to the mortgage, Michael was always readily available to provide answers or direct us to them. Despite some unforeseen changes on our end including shifting our purchase to a different home, he provided us with everything we needed and made the mortgage process nearly free of any stress.

Would highly recommend him to friends and family!

Ryleigh & Jeff
John Doe's Image
I was connected with Michael through my realtor. Michael found me the type of mortgage I was looking, for which helped me purchase my home. The experience was seamless. Michael was always available, customer focused and kept in constant communication with me.

The whole experience working with Michael was perfect.

Boky

SUBSCRIBE TO MY NEWSLETTER

FROM MY INSTAGRAM

NEWS FROM THE DESK OF MICHAEL HALLETT
By Michael Hallett • November 18, 2026
Can’t Find the Right Home After You’re Pre-Approved? There’s Another Option The best place to start any home purchase is with a mortgage pre-approval. It gives you clarity around your budget and lets you shop with confidence. But what happens when you’ve been pre-approved, you know where you want to live—and nothing suitable fits your price range? This is a common challenge, especially for first-time homebuyers. Before buyer fatigue sets in, it may be worth considering a different approach: buying a home that needs work and financing the renovations as part of your mortgage . What Is a Purchase Plus Improvements Mortgage? A purchase plus improvements program allows you to buy a property and include the cost of approved renovations directly in your mortgage. This can be a great solution if: You can’t find a move-in-ready home within budget You’re open to renovations You want to customize the home from the start It opens up more options and can help you get into a location or property that would otherwise be out of reach. How the Process Works While the idea is straightforward, the process itself is structured and requires planning. Here’s a high-level overview: Renovation quotes are required upfront You’ll need detailed quotes for the work you want completed before final mortgage approval. Renovations must add value The lender must be satisfied that the improvements will increase the property’s value accordingly. Funds are reimbursed, not advanced You pay for the renovations initially. Once the work is completed and verified by an appraiser, the lender reimburses you and adds the cost to your mortgage. With the right guidance, this process is very manageable—but it’s important to understand the steps before committing. Is This Program Right for You? Purchase plus improvements isn’t for everyone. Buying a home is already a big undertaking, and adding renovations can increase stress—especially if timelines, budgets, or contractors become challenging. That said, if you’re financially prepared and like the idea of shaping the home to fit your needs, this program can be an excellent way to get more value and flexibility from your purchase. Final Thoughts If you’re struggling to find the right home after being pre-approved, you may not need to lower your expectations—you may just need a different strategy. If you’d like to explore whether a purchase plus improvements mortgage makes sense for you, feel free to connect. I’d be happy to walk you through the process and outline exactly what this option would look like in your situation.
By Michael Hallett • November 11, 2026
Missed a Credit Card or Line of Credit Payment? Here’s What to Do If you’ve missed a payment on a credit card or line of credit and you’re worried about how it might affect your credit—or your future mortgage—this is for you. First things first: 👉 If you currently have an overdue balance, log in and make the minimum payment now. Seriously. Do that first. Everything else can wait. If You’re Only a Few Days Late Here’s the good news: Credit bureaus don’t record late payments until they reach 30 days past due. So if you missed a due date by a few days and paid it as soon as you noticed, it typically won’t show up on your credit report as a late payment—as long as you’re under the 30-day mark. That said, it never hurts to double-check. You can call your credit card company, explain what happened, and confirm the account is back in good standing. If you normally pay on time, they may even reverse the interest charged. It doesn’t hurt to ask. If You’re 30, 60, or 90 Days Behind If payments have gone past 30 days, your credit has likely been impacted—but the situation is still fixable. The most important step is to: Bring all accounts current as soon as possible Make at least the minimum payment on every account The faster you catch up, the more you limit the damage. Ignoring missed payments only makes things worse. If Cash Flow Is Tight If you’re struggling to make payments, communication matters. Contact your lender and keep them informed—even if you can’t pay right away. Lenders are far more willing to work with you when you’re transparent. What hurts your credit most is silence . If lenders don’t hear from you after repeated missed payments, they may write the balance off as bad debt and send it to collections. Collections can significantly impact your credit and stay on your report for years. How This Affects Mortgage Qualification Repeated missed payments can make qualifying for a mortgage more difficult—but timing matters. Once you’re back to making regular, on-time payments: Your credit can improve over time The impact of past mistakes becomes less significant If you’re planning to buy a home in the next couple of years, addressing credit issues early gives you far more options later. Final Thoughts Missing a payment doesn’t mean you’re “bad with money,” and it doesn’t mean homeownership is off the table. What matters most is how quickly you respond and how consistent you are going forward . If you’d like help reviewing your credit report or understanding where you stand from a mortgage perspective, feel free to connect. I’d be happy to walk through it with you and help you create a clear path forward.
By Michael Hallett • November 4, 2026
Porting Your Mortgage: What You Need to Know Before You Rely on It Porting a mortgage means transferring your existing interest rate, remaining term, and outstanding balance from your current home to a new one when you sell and buy again. While some lenders—especially big banks—make porting sound simple, the reality is that porting a mortgage is often complex and far from guaranteed . It’s not a magic solution, and it doesn’t mean you automatically get to keep your old mortgage on your new home. In many ways, porting a mortgage feels like applying for a brand-new one—often with more conditions . Here’s why. 1. You Still Have to Re-Qualify Even though you already have the mortgage, the lender will reassess you. If you: Changed jobs Moved to a new city Are on probation Switched industries or income types …the lender may decline the port. Your previous approval does not carry over automatically. 2. The New Property Must Be Approved The lender also reassesses the new property . Just because they accepted your previous home as collateral doesn’t mean they’ll approve the next one. Expect: A new appraisal A review of the property’s condition Scrutiny around marketability and value If the lender isn’t comfortable with the property, the port can fail. 3. Property Values Rarely Line Up Perfectly Most moves involve a price difference. Buying a more expensive home: You’ll likely need additional funds at a blended rate, which can increase your payment. Buying a less expensive home: You may face a penalty for reducing the mortgage balance. Either scenario can affect your costs. 4. You Still Need a Down Payment Porting doesn’t mean you “swap houses” without cash. You still need: A down payment on the new purchase Closing costs Funds available at the right time This often surprises buyers. 5. Penalties Usually Still Apply (At First) Most lenders: Charge the full mortgage penalty when you sell Refund it only after the port is successfully completed If you’re relying on sale proceeds for your down payment, this temporary penalty can create a cash-flow issue. 6. Timelines Rarely Line Up Perfectly Real estate markets don’t cooperate. You might: Sell quickly but struggle to buy Find a home quickly but wait months to sell Closing dates rarely align, which complicates porting even further. 7. Port Periods Vary by Lender This is where the fine print matters. Depending on the lender, the port window may be: Same day only 30 days 90 days Up to 6 months If the port window is short, both transactions must close within that timeframe—or the port fails. Longer port periods offer flexibility, but also carry the risk of selling first and not finding a replacement property in time. The Bottom Line Porting your mortgage can make sense—especially if you have a strong rate and are buying a similar-priced home. But it is not guaranteed , and it comes with conditions, risks, and timing challenges. Portability is a feature, not a promise. Before you rely on it, it’s important to review all your options , including whether staying with your lender actually makes financial sense. If you’re planning to sell and buy, I’d be happy to walk you through the process, explain your options clearly, and help you decide whether porting is the right move—or if another strategy makes more sense.
SHOW MORE